It is an issue we come across more and more in startups and companies with an international presence: intercompany agreements or, more precisely, the lack of them.
In the first few weeks with a new client we carry out a short legal and tax due diligence, and the same problems almost always come up. One of the most common is not having a defined transfer pricing system, with a written policy setting out methods, margins and mark-ups.
Why do TravelTech companies set up subsidiaries in other countries?
As they expand internationally, TravelTech companies usually set up structures for three reasons:
- Legal: they need a local licence to operate.
- Tax: they are looking for countries with lower corporate income tax, or their volume of business in a country is so high that it pays to set up an entity to recover input VAT.
- Commercial: to have a local presence, obtain better rates from suppliers or customers in that country, or improve their image with investors.
The process is necessary, but the administrative side and its legal and tax implications are often forgotten.
What is an intercompany agreement?
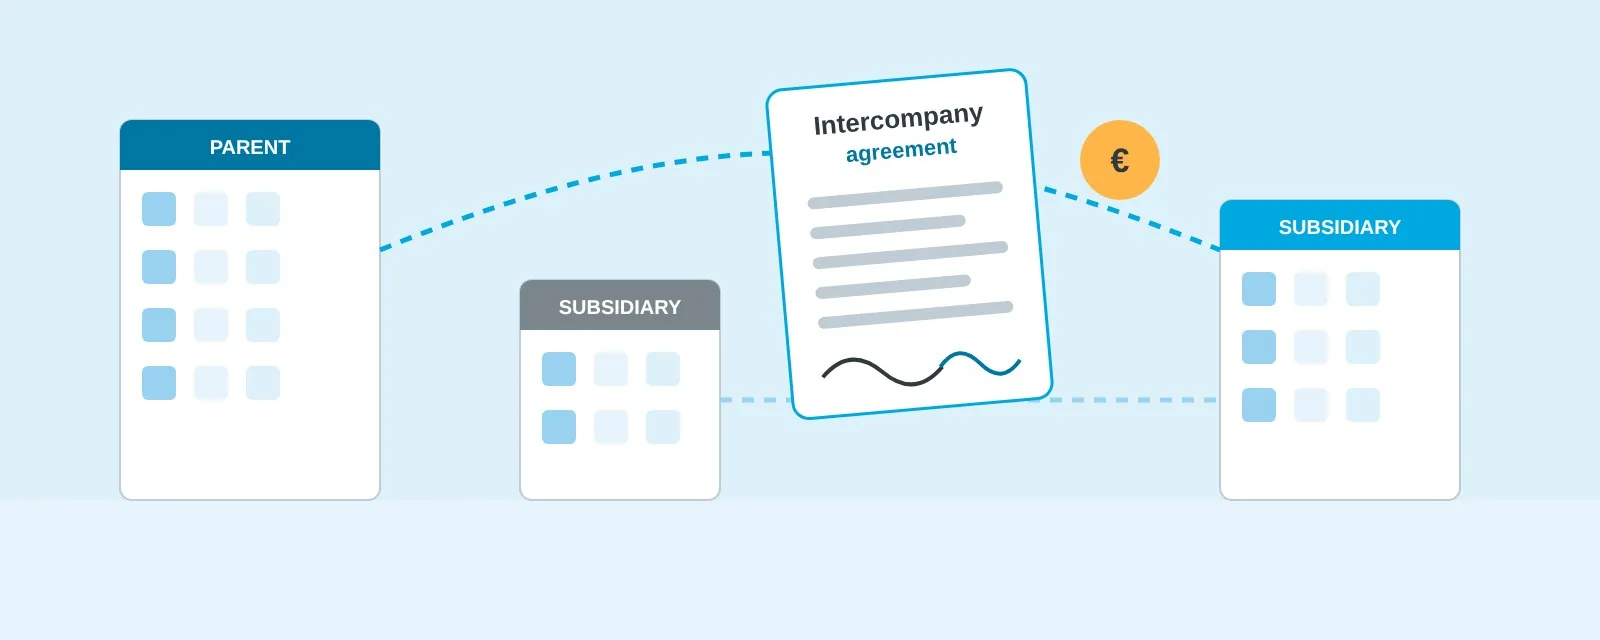
Intercompany agreements are contracts between companies in the same group. They set the terms and conditions of related-party transactions, such as the provision of services or the supply of goods between them. They formalise the transfer pricing policy in a legally binding way and serve as evidence to the tax authorities and other stakeholders that the policy is actually applied.
What happens if you don’t have them?
If the agreements do not exist, are out of date, are poorly drafted or do not reflect what the companies actually do, the tax authorities may challenge them, with possible inspections and penalties.
In addition, the transactions must be documented in the master file or local file supporting the valuation method used. If one country’s tax authority disagrees with the transfer price, it will adjust the company’s profit; if the other country’s authority does not accept that adjustment, double taxation arises.
On top of the tax comes the cost in time and resources of arguing with the tax authorities. In an inspection, it is up to you to prove that your transfer prices have been calculated correctly. It is almost always easier to tie everything up from the start than to defend yourself later.
What are intercompany agreements for?
- Ensuring that transactions with related companies have a legal basis.
- Making the terms and conditions clear.
- Defining who bears each risk.
- Setting how prices are calculated, including adjustments or true-ups after the financial year-end.
- Meeting transfer pricing documentation obligations.
Frequently asked questions
What is an intercompany agreement?
A contract between companies in the same group that sets the terms of their related-party transactions, such as the provision of services or the supply of goods, and formalises the transfer pricing policy.
What is the risk of not having intercompany agreements?
The tax authorities may challenge the prices applied, with possible inspections, profit adjustments, penalties and double taxation if the other country does not accept the adjustment.
This article is for information only and does not constitute legal or tax advice.